How to finance a park model home in 2026: buyer’s guide
Financing a park model home presents unique challenges because these tiny dwellings fall into a gray area between recreational vehicles and manufactured housing. Many buyers struggle to find lenders who understand the product or offer competitive terms. This guide breaks down your financing options, eligibility requirements, and step-by-step strategies to secure affordable funding that makes sustainable living accessible.
Table of Contents
- Understanding Park Model Home Financing Basics
- Preparing To Apply: Eligibility, Budgeting, And Pre-Approval Steps
- Executing Your Financing Plan: Choosing Lenders And Loan Types
- Common Financing Pitfalls And Verifying Loan Terms
- Explore Eco-Friendly Park Model Homes And Financing Solutions
- How To Finance A Park Model Home: Frequently Asked Questions
Key takeaways
| Point | Details |
|---|---|
| Classification matters | Park model homes under 400 sq ft are financed as RVs, while larger ones qualify as manufactured homes with different loan products. |
| Mortgage versus chattel loans | Mortgage loans offer lower rates and longer terms but require land ownership, while chattel loans use only the home as collateral. |
| Pre-approval advantage | Getting pre-approved at multiple lenders gives you negotiation power and clarifies your budget ceiling before shopping. |
| Debt-to-income ratio counts | Lenders calculate your monthly debts plus new loan payment plus lot rent divided by gross income to determine eligibility. |
| Refinancing flexibility | After purchase, refinancing can lower monthly payments or fund land acquisition. |
Understanding park model home financing basics
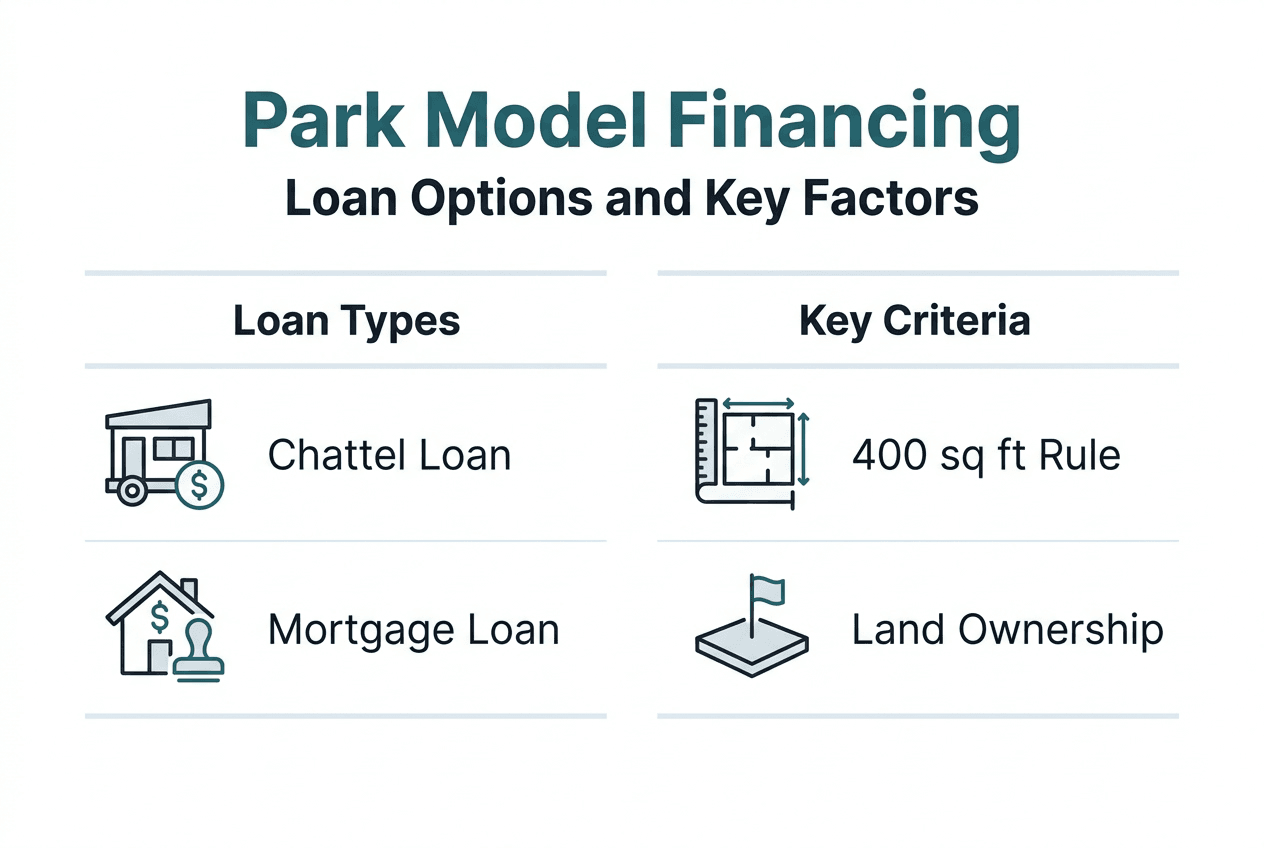
Classifying your park model correctly determines which loan products you can access. Homes under 400 sq ft typically receive financing as recreational vehicles because lenders treat them like travel trailers. Larger models that meet specific construction standards qualify for manufactured home loans with more favorable terms.
To be eligible for a manufactured home loan, your home must meet the HUD code, the federal safety standard for manufactured homes established on June 15, 1976. This certification opens doors to mortgage-style financing if you own land or install the home permanently on a foundation.
Chattel loans represent the most common financing path for park model buyers who rent their lot. These home-only loans use the structure as collateral while you pay monthly lot rent separately to the park owner. Expect shorter repayment periods of 10 to 15 years and higher interest rates compared to traditional mortgages.
Mortgage loans become available when you own the land where your park model sits or permanently install it on a foundation you own. These products mirror conventional home loans with 15 to 30-year terms and significantly lower rates. Understanding park model home terms helps you communicate effectively with lenders and avoid confusion about your financing needs.
Most park model buyers in communities pay their loan payment for the home itself plus a separate monthly lot rent to the park. This dual payment structure affects your budget calculations and debt-to-income ratio when lenders evaluate your application. Knowing these financing basics positions you to choose the loan type that aligns with your ownership situation and financial goals.
Preparing to apply: eligibility, budgeting, and pre-approval steps
Lenders calculate your debt-to-income ratio including lot rent to verify you can afford the loan. This ratio divides your total monthly debt obligations plus your new loan payment plus lot rent by your gross monthly income. Most lenders prefer ratios below 43%, though some accept higher percentages with strong credit scores.
Follow these steps to strengthen your application:
- Collect recent pay stubs, tax returns, and bank statements to prove income stability.
- Verify your park model meets HUD code requirements if pursuing manufactured home financing.
- Calculate your total monthly obligations including existing debts, projected loan payment, and lot rent.
- Check your credit report for errors and address any issues before applying.
- Research down payment requirements, which typically range from 5% to 20% depending on loan type.
Applying for pre-approval at multiple lenders provides a clear budget ceiling and exact rate tier before you shop for your home. This hard number empowers negotiation because sellers and dealers see you as a serious buyer with verified funding. Pre-approval also reveals potential obstacles early, giving you time to improve credit or adjust your budget.
Pro Tip: Complete pre-approval at three different lenders to compare offers and leverage competition for better terms. Credit inquiries within a 14-day window count as a single inquiry, protecting your credit score.
Avoid letting dealers run your credit until you’ve agreed on the out-the-door purchase price in writing. Some dealers use credit checks as a selling tactic, creating urgency or steering you toward their higher-priced financing partners. Understanding the benefits of park model homes helps you stay focused on value rather than dealer pressure tactics. Reviewing RV loan terminology ensures you understand the financing language lenders use.
Executing your financing plan: choosing lenders and loan types
Comparing loan products reveals significant differences in total cost and monthly payments. This table shows how chattel and mortgage loans stack up:
| Feature | Chattel Loan | Mortgage Loan |
|---|---|---|
| Typical term | 10-15 years | 15-30 years |
| Interest rate | 7%-10% | 4%-7% |
| Land ownership | Not required | Required |
| Down payment | 10%-20% | 5%-20% |
| Monthly payment | Higher due to shorter term | Lower due to longer term |
Dealer financing carries markups ranging from 1% to 3% above wholesale rates because dealers earn commissions on loans they originate. These seemingly small percentage increases compound to thousands of dollars over the loan term. Skip dealer financing when possible and secure your own loan from a direct lender.
Credit unions, banks, and specialized manufactured home lenders offer the most competitive rates for park models. Credit unions often provide personalized service and flexible underwriting for members. Banks bring competitive rates for borrowers with strong credit. Specialized lenders understand park model nuances and offer products tailored to tiny home buyers.
Chattel loans feature higher rates and shorter terms but don’t require land ownership, making them accessible for park residents. Mortgage loans deliver lower monthly payments over extended terms but mandate land ownership or permanent installation.
Consider these government-backed loan options if you qualify:
- FHA loans accept lower credit scores and smaller down payments for manufactured homes meeting Title II requirements.
- VA loans offer zero down payment financing for eligible veterans purchasing qualified manufactured homes.
- USDA loans provide financing in designated rural areas with competitive terms for income-qualified buyers.
Pro Tip: Ask lenders about refinancing policies at the time of origination. Some lenders make refinancing easier than others, which matters if you plan to purchase land later or want to lower payments when rates drop. The Florida park model buyer’s guide covers regional financing considerations, while best park model homes in Florida showcases quality options worth financing.
Common financing pitfalls and verifying loan terms
Many buyers focus exclusively on interest rate while ignoring APR, which includes the interest rate plus most lender fees. Understanding APR versus interest rate helps you compare the true cost across different loan offers. A loan with a 6% rate but high fees might have a 7.2% APR, making it more expensive than a 6.5% rate loan with minimal fees and a 6.8% APR.
Short loan terms on chattel products create deceptively affordable-looking homes with crushing monthly payments. A $50,000 loan at 8% over 10 years costs $606 monthly, while the same loan over 15 years drops to $478 monthly. The longer term costs more in total interest but makes home ownership realistic for more buyers.
Never let a dealer run your credit before the out-the-door purchase price is agreed in writing.
Avoid these common mistakes that cost buyers thousands:
- Ignoring lot rent when calculating affordability, leading to budget strain after purchase.
- Skipping pre-approval and losing negotiation leverage with sellers.
- Accepting the first loan offer without comparing at least three lenders.
- Overlooking prepayment penalties that trap you in high-rate loans.
- Failing to verify HUD code compliance before applying for manufactured home loans.
Reviewing loan terms carefully prevents expensive mistakes and ensures your financing aligns with your long-term goals. Read every document before signing and ask questions about anything unclear. Understanding park model home costs helps you budget realistically for both purchase price and ongoing expenses.
Double check these elements in your loan agreement: APR, monthly payment amount, loan term length, prepayment penalty clause, balloon payment requirements, and total interest paid over the loan life. A 30-minute review now prevents years of regret.
Explore eco-friendly park model homes and financing solutions
Ecolife Homes specializes in sustainable eco-friendly park model tiny homes built with premium steel construction and fully customizable designs. Our team brings over 21 years of combined expertise in civil engineering and home construction to every project. We handle permitting, delivery, and installation across the USA, making your transition to tiny living seamless.
Our experts provide guidance on tiny home financing to help you navigate the loan process and find affordable solutions. We work with buyers at every stage, from choosing the right model to understanding which financing products match your situation. Explore our range of customizable designs and discover who chooses tiny homes to see if park model living fits your lifestyle and budget.
How to finance a park model home: frequently asked questions
What is the difference between a chattel loan and a mortgage loan for park model homes?
Chattel loans use only the home as collateral and typically run 10 to 15 years with higher interest rates around 7% to 10%. Mortgage loans require land ownership or permanent installation, offer 15 to 30-year terms, and feature lower rates from 4% to 7%.
Can I get a loan if I don’t own the land where the park model is placed?
Yes, chattel loans specifically serve buyers who rent their lot in a park community. These home-only loans let you finance the structure while paying separate monthly lot rent to the park owner.
How does the 400-square-foot rule affect my financing options?
Park models under 400 sq ft are classified and financed as recreational vehicles with RV loan products. Models above this threshold may qualify as manufactured homes with access to mortgage-style financing if they meet HUD code requirements.
Why is pre-approval important before buying a park model home?
Pre-approval gives you a verified budget ceiling and exact interest rate before shopping, which strengthens negotiations with sellers. It also reveals potential eligibility issues early, letting you address credit problems or adjust your down payment before finding your ideal home.
Can I refinance my park model home loan later?
Yes, refinancing options let you lower monthly payments when rates drop or extend your loan term for better cash flow. Some buyers refinance to fund land purchases, converting their chattel loan into a mortgage loan with better terms.
What documents do lenders require for park model financing?
Expect to provide recent pay stubs, two years of tax returns, bank statements showing reserves, proof of HUD code compliance for the home, and details about the land or park where you’ll place the model. Lenders verify your debt-to-income ratio and credit score during underwriting.
Recommended
- Florida Park Model Tiny Homes: Complete Buyer’s Guide (2026) – Ecolife Homes – Park Model Home Manufacturer – Florida – USA
- Why Buying a Park Model Tiny Home in 2026 Is a Smart Move for Bonus Depreciation Tax Benefits – Ecolife Homes – Park Model Home Manufacturer – Florida – USA
- Why Park Model Tiny Homes Are a Game-Changer in 2026 – Ecolife Homes – Park Model Home Manufacturer – Florida – USA
- Why Choose a Park Model Tiny Home? – Ecolife Homes – Park Model Home Manufacturer – Florida – USA