Affordable housing solutions in Florida: top options for 2026
TL;DR:
- Florida’s housing market presents significant affordability challenges for families and first-time buyers due to rising prices and complex program options. A layered approach combining state and local funding, alternative ownership models like land trusts and park model tiny homes, and strategic planning can improve access and long-term stability. Successful navigation requires flexibility, understanding of program eligibility, and collaboration with local agencies to leverage multiple resources effectively.
Florida’s housing market has become one of the toughest in the country, with median home prices climbing well above what many working families, retirees, and first-time buyers can realistically afford. The challenge isn’t just the price tags. It’s figuring out which state programs apply to you, how innovative ownership models actually work, and whether an alternative housing type like a park model tiny home could genuinely solve your affordability problem. This article cuts through the noise and lays out the most effective, real-world solutions available to Florida homebuyers and investors in 2026, evaluated by impact, accessibility, and long-term value.
Table of Contents
- How to evaluate affordable housing solutions in Florida
- State and local financing programs: SHIP, FHFC, and mortgage support
- Alternative homeownership models: land-lease, community land trusts, and park model tiny homes
- How Florida communities and local governments enhance housing affordability
- Which solutions scale? Comparing impact and real-world fit for Florida’s housing crunch
- Why affordable doesn’t always mean accessible: hard truths and next steps
- Take the next step with tailored, sustainable home solutions
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Layered solutions work best | Combining financing, ownership, and community resources yields the most affordable path to homeownership in Florida. |
| Park models offer flexibility | Customizable park model tiny homes provide a lower-cost, sustainable alternative for modern buyers and investors. |
| Leverage local partnerships | Local government and public-private partnerships unlock grant funds and support long-term affordability. |
| Check eligibility details | Review credit, income, and buyer status requirements early to avoid surprises when applying for support programs. |
How to evaluate affordable housing solutions in Florida
To help you navigate the options ahead, let’s break down what matters most when evaluating affordable housing solutions in Florida. Not every program or housing model will be the right fit, and making a smart decision requires measuring each option against a consistent set of criteria.
The most useful criteria for evaluating affordable housing solutions include:
- Funding availability: Is the program actively funded and accepting applications right now?
- Program scalability: Does it serve a broad range of buyers, or only a narrow eligibility window?
- Ownership stability: Does the model give you long-term security, not just a short-term discount?
- Long-term affordability: Will the costs remain manageable five or ten years from now?
- Sustainability: Is the home built or designed to lower your operating costs over time?
It’s also important to separate state-level programs from local ones. State programs administered by agencies like the Florida Housing Finance Corporation tend to have wider reach, while local programs can offer more flexible terms and faster processing for buyers in specific counties.
A practical tiny house financing guide can help you understand how alternative housing types stack up against conventional mortgage options before you commit to a direction.
As OPPAGA recommends, prioritizing a layered menu of solutions tends to produce the best results. That means combining grant assistance with an alternative ownership model, or pairing a state loan program with an eco-friendly home type that lowers your monthly costs.
Pro Tip: Don’t rely on a single program or solution. Stack a down payment assistance grant with a lower-cost park model home and a community land trust arrangement, and you could dramatically reduce both your upfront and ongoing housing costs.
State and local financing programs: SHIP, FHFC, and mortgage support
With a clear framework established, let’s dive into the specific public and local financing programs that can make homeownership realistic. Florida invests heavily in housing assistance, and understanding how these programs work is the first step to using them effectively.
Florida’s affordable housing support is delivered through state programs administered primarily by the Florida Housing Finance Corporation (FHFC) and FloridaCommerce, with SHIP and FHFC programs funding both rental and homeownership opportunities across the state.
SHIP: statewide down payment help
Florida’s SHIP program provides down payment and closing cost assistance to eligible first-time homebuyers across all 67 counties and 55 entitlement cities. The assistance amounts typically range from $10,000 to $70,000 depending on your county, income level, and local program design. These funds don’t always have to be repaid immediately. Many counties structure SHIP assistance as a deferred second mortgage, meaning repayment kicks in only when you sell or refinance.
FHFC: a major production engine
Between 2020 and 2024, FHFC program expansions added 64,907 new rental units and served 37,617 homeowners statewide. In the same period, SHIP funds supported 5,970 rental households and 13,523 homeowners. These numbers demonstrate genuine scale, not just a pilot program.
| Program | Who it helps | Key benefit | Eligibility highlights |
|---|---|---|---|
| SHIP | First-time buyers, renters | $10,000–$70,000 assistance | Income limits, county-specific |
| FHFC | Renters and buyers | New units + affordable loans | Varies by development |
| Homeownership Loan Program | First-time buyers | Up to $35,000 at 0% interest | Credit score 640+, income limits |
The Homeownership Loan Program
Florida’s Homeownership Loan Program provides affordable first-mortgage loans plus down payment and closing cost assistance through participating lenders. Eligible buyers can receive up to $35,000 as a deferred second mortgage at 0% interest. To qualify, you need a minimum credit score of 640, first-time homebuyer status, and income that falls within county-specific limits.
“Florida’s layered approach to housing finance, combining SHIP down payment assistance with FHFC-backed first mortgages, gives eligible buyers access to resources that weren’t possible through private lending alone.”
If you’re exploring lower-cost home types to pair with these programs, affordable tiny homes in Florida and modular housing options are two categories worth researching alongside your financing search.
Alternative homeownership models: land-lease, community land trusts, and park model tiny homes
Financing isn’t the only path to affordability. Let’s look at innovative ownership structures and home types that can make a real difference, especially for buyers who don’t qualify for conventional loans or who want to reduce long-term costs from the start.
Community land trusts (CLTs)
A community land trust is a nonprofit organization that owns land on behalf of the community. When you buy a home through a CLT, you purchase the structure but lease the land beneath it at a low monthly rate. Because you’re not paying for the land, the purchase price drops significantly. The trade-off is a resale restriction: when you sell, the price must remain within an affordable range so the next buyer benefits too.
CLT land-lease and resale frameworks are recognized as one of the most reliable ownership models for protecting long-term affordability, according to OPPAGA’s analysis of Florida housing programs.
Land-lease communities
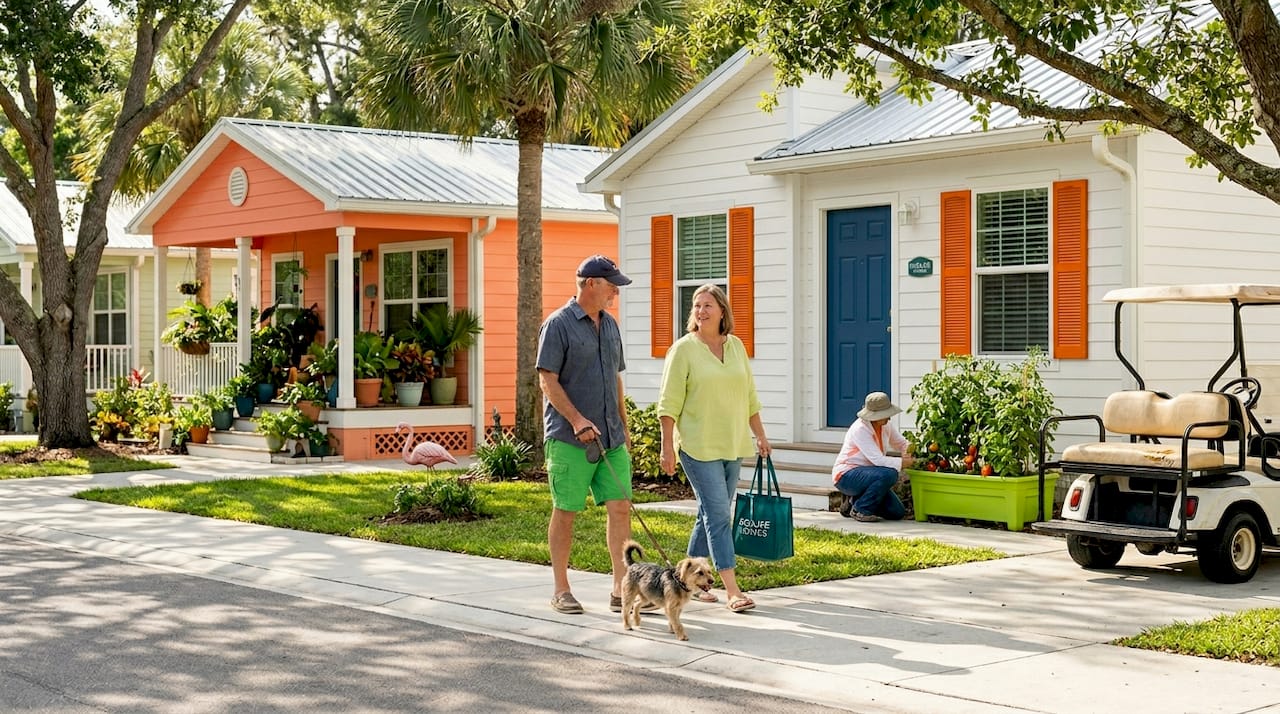
In a land-lease arrangement, you buy or own the home outright but pay monthly ground rent for the lot it sits on. This is common in manufactured and park model home communities. The upfront cost is much lower than buying land and a home together, but the ongoing ground rent is a real cost to factor into your budget. The key advantage is that qualifying is typically easier than a traditional mortgage.
Park model tiny homes
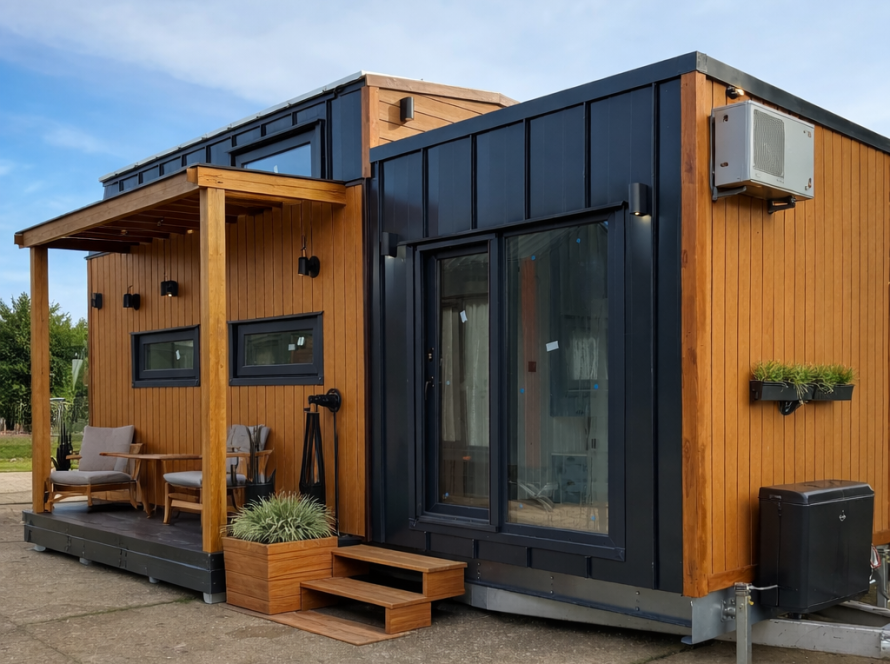
Park model tiny homes are factory-built, move-able dwellings that are typically under 400 square feet. They’re designed with full kitchen, bath, and sleeping areas and can include features like energy-efficient appliances, modern finishes, and steel chassis construction for durability. The purchase price is substantially lower than a site-built home, and when placed in a land-lease community, the total monthly cost can be very manageable.
| Ownership model | Upfront cost | Monthly cost | Resale restrictions | Stability |
|---|---|---|---|---|
| Community land trust | Low to moderate | Low land lease | Yes, capped resale | High |
| Land-lease park model | Low | Ground rent applies | No restrictions | Moderate to high |
| Traditional purchase | High | Mortgage + taxes | None | High |
| Rental | None | Rent (variable) | N/A | Low |
Pro Tip: If you don’t qualify for a standard mortgage, a land-lease park model home placed in a tiny home community can be an effective bridge to stable housing. Many buyers later apply SHIP funds or other grants toward a traditional purchase once they’ve built credit and savings.
Before committing to any model, read through a detailed tiny home buying guide that covers real costs, zoning, and installation requirements specific to Florida.
How Florida communities and local governments enhance housing affordability
Ownership models are powerful, but when combined with local and state partnership resources, your options expand even further. Local governments across Florida play an active role in stretching housing dollars and making more options available to residents.
Local SHIP administration plans describe SHIP as a tool for local governments to produce and preserve affordable housing, including strategies that leverage local resources, reduce housing costs, and partner with private developers and nonprofits to fill gaps the market won’t.
What local SHIP plans actually do
Local housing action plans (LHAPs) go beyond writing checks. They outline how a city or county will use its SHIP allocation across multiple strategies:
- Combining local, public, and private funds to stretch every dollar further
- Accessing federal grants like Community Development Block Grants (CDBG) using SHIP as a local match
- Preserving existing affordable homes through repair assistance and weatherization
- Supporting owner-occupied rehabilitation to keep long-time residents in their homes
“Local housing plans that layer SHIP funds with federal grant matches can effectively double or triple the impact of each state dollar spent, making more units available at a lower net cost per household.”
How to tap into local programs
Here’s a practical sequence for accessing these resources:
- Contact your local SHIP administrator. Every county and entitlement city in Florida has one. They can tell you exactly what programs are active and how to apply.
- Apply for layered support. Ask specifically whether you can combine down payment assistance with a home repair grant or a second mortgage program.
- Review local housing inventories. Some LHAPs maintain lists of available affordable units, CLT homes, or land-lease lots that aren’t widely advertised.
For buyers focused on sustainability, pairing local program assistance with eco homes in Florida can reduce your utility costs long after your grant funds are spent. Affordable tiny homes Florida built with energy-efficient materials are a natural fit for this kind of layered approach.
Which solutions scale? Comparing impact and real-world fit for Florida’s housing crunch
Let’s pull it all together with a direct, side-by-side look at what’s really making a difference for Florida families. Scale matters because a program that only helps a few hundred people per year won’t solve a statewide crisis.
Florida’s state housing strategy has measurable throughput. FHFC-reported outcomes show tens of thousands of rental units added and tens of thousands of homeowners served in just a four-year period, giving us a strong baseline for comparing which approaches are making the biggest dent.
| Solution | Scale | Best for | Key limitation |
|---|---|---|---|
| SHIP assistance | Very high (statewide) | First-time buyers | Oversubscribed in some counties |
| FHFC rental programs | Very high (64,907 units) | Renters and investors | Rental, not ownership focused |
| Homeownership Loan Program | Moderate | Buyers with 640+ credit | Strict eligibility criteria |
| Community land trusts | Growing but limited | Long-term buyers | Limited inventory statewide |
| Land-lease park model homes | High potential | Entry-level buyers | Ground rent adds monthly cost |
| Park model tiny homes (owned land) | Growing | Buyers and investors | Zoning varies by location |
For investors, the FHFC rental unit pipeline and park model tiny homes both offer strong potential. Cheap tiny homes options in Florida are increasingly attractive to investors developing vacation rental properties or accessory dwelling units.
The best decision matrix is simple. If you have a credit score of 640 or above and limited savings, start with SHIP and the Homeownership Loan Program. If your credit is still building, look at land-lease park model communities. If you want long-term affordability with resale protection, explore CLT options in your county. If you’re an investor looking for faster entry and high flexibility, a park model tiny home on owned land or a land-lease lot is worth serious consideration.
Why affordable doesn’t always mean accessible: hard truths and next steps
After comparing the numbers, it’s worth pausing for a realistic look at the road ahead and what really drives results. Florida’s programs are genuinely impressive in scale, but impressive doesn’t always mean easy to access.
Here’s the uncomfortable truth: SHIP funding gets oversubscribed. In many counties, waitlists fill up within days of opening. That means a buyer who qualifies on paper might still wait months before receiving assistance. The eligibility rules also change annually based on area median income updates, so you might qualify in one quarter and fall just above the threshold the next.
The same applies to park model and CLT options. Not every county has an active land trust program. Zoning rules for park model tiny homes vary widely, and some municipalities have restrictions that make placement difficult even when you have the financing in place. The solution isn’t to give up on these tools. It’s to approach your housing search with a layered strategy and genuine flexibility.
Savvy buyers plan for the long term but build in contingency options. That means applying for multiple programs simultaneously, staying in close contact with local SHIP administrators, and being open to alternative home types when traditional purchase paths are blocked. Exploring what makes a sustainable living blueprint practical for your situation is a useful exercise because energy-efficient homes genuinely lower your long-term cost of living, even when the purchase price is similar.
The buyers who succeed in Florida’s market right now are the ones who treat affordability as a system to work, not a single door to knock on.
Take the next step with tailored, sustainable home solutions
If you’re inspired to explore next steps, from tiny home communities to modular builds, expert guidance helps turn vision into reality.
At Ecolife Homes, we’ve spent over 21 years combining civil engineering expertise with a passion for sustainable, accessible housing. We design and manufacture premium steel park model tiny homes right here in Florida, and we handle everything from permitting to final installation. Whether you’re a first-time buyer navigating SHIP eligibility or an investor looking for a flexible, high-quality rental unit, our team can help you find the right fit.
Start by exploring Tiny Homes Life to see how real people are living affordably and comfortably in Florida’s park model communities. Then check out our sustainable housing guide for a deep look at how eco-friendly design choices can lower your total cost of homeownership over time. When you’re ready to talk specifics, our team is here to walk you through design options, financing considerations, and local installation requirements.
Frequently asked questions
How much down payment assistance is available to first-time homebuyers in Florida?
SHIP assistance ranges from $10,000 to $70,000 in down payment and closing cost help for eligible first-time buyers across Florida’s 67 counties and 55 entitlement cities.
What are park model tiny homes and are they legal in Florida?
Park model tiny homes are compact, factory-built dwellings under 400 square feet that include full living amenities. They are legal in many Florida communities when placed in properly zoned areas with correct installation permits.
Are there income limits to qualify for Florida’s Homeownership Loan Program?
Yes, program eligibility requires meeting county-specific income and purchase price limits, a minimum 640 credit score, and first-time homebuyer status. The assistance can reach up to $35,000 as a deferred second mortgage.
How do community land trusts (CLTs) keep housing affordable?
CLTs retain ownership of the land and sell only the home structure to buyers, then apply resale restrictions so future buyers also benefit from a below-market purchase price.
Can SHIP funds be used alongside other state and federal housing programs?
Yes. SHIP funds can be leveraged as a local match to access federal housing grants like CDBG, multiplying the impact of each program dollar and opening access to a wider range of housing opportunities.